A police bodycam recording has surfaced showing a woman in a holding room attempting a breathalyser test, with a text overlay claiming the individual is a "heavily intoxicated" DoorDash driver. The footage, which carries a March 2025 timestamp, offers a stark glimpse into the tense, clinical process of a roadside sobriety check — and raises immediate questions about the insurance and legal fallout that follows.
Watch Full Video
Overview of the incident and the key facts
- The bodycam footage, marked with an AXON BODY 4 timestamp, shows a woman in a white tank top being instructed through a breath test.
- An officer's voice can be heard coaching the subject, stating: "You're going to have to blow for a long time, and I'm going to tell you, I'll coach you through."
- A text overlay on the video identifies the subject as a DoorDash driver who is "heavily intoxicated."
- The setting appears to be a sterile holding room or processing area, with an Intoxilyzer machine visible in the frame.
- The footage carries a time stamp of 02:04:00 on 14 March 2025, placing the incident in the early hours of the morning.
The anatomy of a late-night traffic stop
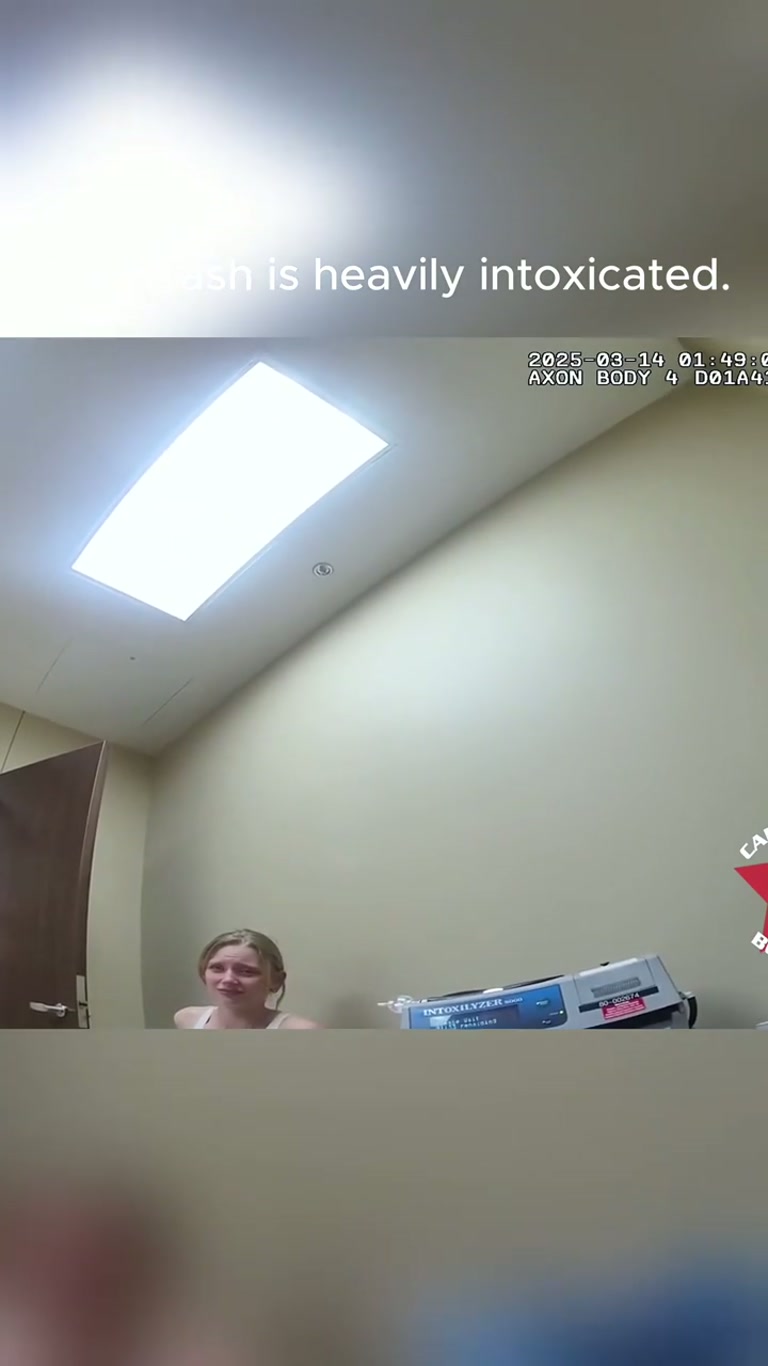
The camera shakes slightly as the officer adjusts his grip, the bodycam lens capturing the stark fluorescence of a holding room. It is just after 2am on 14 March 2025, and the subject — a woman with blonde hair pulled back, wearing a simple white vest top — stands against a pale wall. The atmosphere is thick with the kind of weary tension that only exists in the small hours, when the rest of the world is asleep and the machinery of law enforcement grinds on. An Intoxilyzer 8000, a bulky grey machine with tubes and a digital display, sits on a surface nearby, waiting to deliver its verdict.
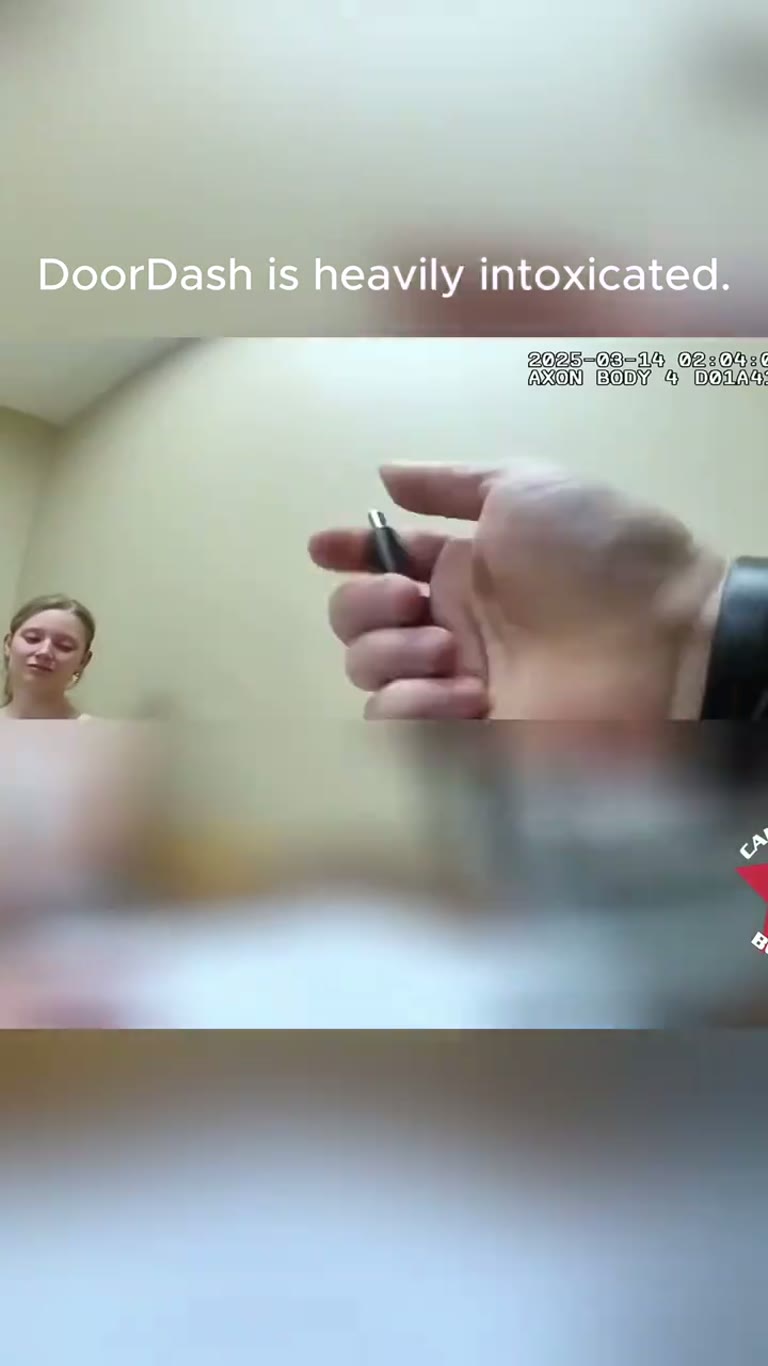
The audio crackles with the officer's voice, calm but firm. "So this right here, this is the first breath," he says, demonstrating the device. "That's the way this is, okay? You're going to have to blow for a long time, and I'm going to tell you, I'll coach you through." The words are procedural, almost gentle, but they carry the weight of what is at stake. This is not a conversation; it is the beginning of a legal process that could unravel a person's livelihood in a matter of minutes. The woman listens, her expression unreadable in the low-resolution frames, her arms resting at her sides.
The text overlay, added later by whoever circulated the clip, is blunt: "DoorDash is heavily intoxicated." It is a jarring juxtaposition — the mundane familiarity of a food delivery brand, the clinical reality of a drunk driving investigation. The footage does not show the traffic stop itself, nor the driving that preceded it. It begins in medias res, inside the room, with the machine already primed. What we see is not the chaos of the road, but the quiet, bureaucratic aftermath. It is a reminder that every arrest has a paper trail, and every breath test is a data point.
The officer's hand, clad in a dark watch, is visible in the foreground, holding a small black mouthpiece. He gestures towards the machine, guiding the woman through the procedure. There is no shouting, no struggle, no dramatic resistance. Just the slow, deliberate mechanics of a sobriety test. Yet the stakes could not be higher. For a gig-economy worker, a driving ban is not just an inconvenience — it is an existential threat to their income. For the insurance industry, it is a red flag that triggers a cascade of financial consequences.
The gig economy's hidden liability trap
The gig economy has transformed how millions of people earn a living, but it has also created a labyrinth of insurance grey areas. When a driver is accused of being intoxicated while on the job, the question of who pays becomes extraordinarily complicated. DoorDash, like many platforms, classifies its drivers as independent contractors rather than employees. This distinction matters enormously when things go wrong. If a driver is involved in an accident while intoxicated, the platform's commercial insurance policy — which typically provides coverage during active deliveries — may be voided entirely.
Most gig-economy platforms require drivers to maintain their own personal car insurance. However, standard personal policies almost always exclude commercial use. This means a driver who is delivering food without a commercial rider may find their claim denied, even before the question of intoxication is raised. If the driver is then found to be over the legal limit, the situation spirals further. Insurers in both the US and UK treat driving under the influence as a fundamental breach of policy conditions. The result is a perfect storm: no cover from the platform, no cover from the personal insurer, and a mountain of liability that falls squarely on the individual.
The financial consequences can be devastating. In the UK, a conviction for drink-driving typically results in a minimum 12-month disqualification, an unlimited fine, and potentially a prison sentence. In the US, penalties vary by state but can include jail time, hefty fines, and the mandatory installation of an ignition interlock device. For a delivery driver, the loss of a licence means the immediate loss of income. Without a car, they cannot work. Without work, they cannot pay the fines or the legal fees. It is a downward spiral that the insurance industry knows all too well.
Moreover, the platform itself may pursue the driver for damages. If DoorDash is named in a lawsuit arising from an accident caused by an intoxicated driver, the company could seek to recover its losses from the individual. This is where liability insurance becomes critical — and where many drivers discover, too late, that they are not covered. The bodycam footage does not show what happened before the test, but the presence of the Intoxilyzer suggests that law enforcement had already formed a suspicion. The insurance implications begin the moment that suspicion is formalised.
The forensic reality of the Intoxilyzer
The machine visible in the footage is an Intoxilyzer 8000, a breath alcohol testing device widely used by law enforcement agencies across the United States. It works by measuring the amount of alcohol in a person's breath, which correlates with blood alcohol concentration (BAC). The legal limit for driving in most US states is 0.08%, while in the UK it is 35 microgrammes of alcohol per 100 millilitres of breath (roughly equivalent to 0.08% BAC). The Intoxilyzer is designed to provide a precise, admissible reading that can be used as evidence in court.
The officer's instruction — "you're going to have to blow for a long time" — is standard procedure. A breath test requires a sustained, forceful exhalation to ensure the sample is deep lung air, not just air from the mouth. If the subject fails to blow hard enough, the machine will register an error, and the test may need to be repeated. This is why officers "coach" subjects through the process. It is not a courtesy; it is a requirement for obtaining a valid sample. A faulty test can be challenged in court, potentially undermining the entire case.
From an insurance perspective, the breath test result is the linchpin. If the reading is above the legal limit, the driver's policy is effectively void. If the reading is below the limit, the driver may still face charges — such as driving while impaired by drugs — but the insurance consequences may differ. In some cases, an insurer may still refuse to pay out if the driver was deemed to be driving recklessly, regardless of the breath test result. The footage does not reveal the outcome of the test, leaving the viewer to wonder what the machine eventually displayed.
The presence of the machine also raises questions about the location. Is this a police station, a mobile command unit, or a hospital? The pale walls and the ceiling light suggest a sterile, institutional environment. The timestamp — 02:04:00 — indicates the early hours of the morning, a time when fatigue and alcohol combine to create the highest risk of accidents. For the insurance industry, late-night driving is a known risk factor, and claims data consistently shows that accidents are more severe and more frequent during these hours. The footage, therefore, is not just a legal document; it is a snapshot of a high-risk moment.
What happens next for the driver and the platform
The immediate aftermath of a positive breath test is a cascade of legal and financial events. The driver is likely to be arrested, processed, and released on bail pending a court appearance. Their vehicle may be seized or towed, incurring storage fees that mount daily. If they are a gig-economy worker, their account may be deactivated by the platform, cutting off their income stream instantly. DoorDash, like other platforms, has terms of service that prohibit driving under the influence. A violation can result in permanent removal from the platform.
For the driver's personal insurance, the consequences are equally severe. Most policies require the policyholder to notify the insurer of any accident or conviction. Failure to do so can result in the policy being cancelled retroactively. If the insurer discovers the drink-driving conviction independently, they may cancel the policy and refuse to pay any outstanding claims. In the UK, the Motor Insurers' Bureau (MIB) may step in to compensate victims of uninsured drivers, but this does not absolve the driver of their liability. The MIB can pursue the driver for the costs it incurs.
The platform's own insurance may also be affected. DoorDash provides commercial auto insurance for drivers who are actively on a delivery, but this cover is typically secondary to the driver's personal policy. If the personal policy is voided due to intoxication, the platform's insurer may become the primary responder. However, the platform's insurer will almost certainly seek to recover any payouts from the driver. This is known as subrogation, and it can result in a civil judgment against the driver that follows them for years.
The financial implications for the driver are grim. Legal fees, fines, court costs, and the loss of income can easily run into tens of thousands of pounds or dollars. Without a car, the driver cannot work. Without work, they cannot pay the fines. It is a cycle that traps many people in a cycle of debt and unemployment. The insurance industry is aware of this dynamic, but its primary responsibility is to its policyholders — and in this case, the policyholder is the driver who has breached the terms of their cover.
Which insurance policy — personal, commercial, or platform-provided — will ultimately be responsible for any claims arising from this event?
Insurance and who pays
In the event of a drink-driving incident involving a gig-economy driver, the insurance landscape is a minefield. The first layer is the driver's personal car insurance. Standard policies in the UK and US almost universally exclude liability arising from criminal acts, including driving under the influence. This means that if the driver is convicted, their insurer is likely to refuse to indemnify them. The policy may be cancelled, and the driver may struggle to obtain affordable cover in the future.
The second layer is the platform's commercial insurance. DoorDash, for example, provides liability cover for drivers during active deliveries. However, this cover is contingent on the driver complying with the law and the platform's terms of service. If the driver was intoxicated, the platform's insurer may deny cover on the grounds that the driver was in breach of contract. The platform itself may also seek to recover any losses from the driver.
The third layer is the victim's own insurance. If the intoxicated driver causes an accident, the victim may claim on their own policy. Their insurer will then seek to recover the costs from the at-fault driver. If the at-fault driver is uninsured or cannot pay, the victim's insurer may absorb the loss, but this can affect the victim's no-claims bonus and future premiums.
In the UK, the Motor Insurers' Bureau (MIB) provides a safety net for victims of uninsured and untraced drivers. However, the MIB does not cover damage to the victim's own vehicle — it only covers personal injury and damage to property that is not the victim's own. This means that a victim of an uninsured drink-driver may still face significant out-of-pocket costs.
The excess, or deductible, is another crucial factor. Even if a claim is approved, the policyholder is usually required to pay the first portion of any claim. For drink-driving incidents, the excess may be significantly higher, or the claim may be denied altogether. It is essential for drivers to understand the specific terms of their policy before an incident occurs.
For anyone involved in a similar situation, the steps to making a claim are as follows: first, report the incident to the police and obtain a crime reference number. Second, notify your insurer as soon as possible, providing all relevant details. Third, gather evidence, including photographs, witness statements, and any dashcam or bodycam footage. Fourth, cooperate fully with the insurer's investigation. Finally, if the claim is denied, seek independent legal advice.
The insurance industry's response to drink-driving is unequivocal: it is a breach of the fundamental terms of cover. Whether the driver is a gig-economy worker or a traditional employee, the financial consequences are severe. The footage serves as a stark reminder that the decisions made in the early hours of the morning can have repercussions that last for years.
What do you think should happen to a delivery driver caught drink-driving — should the platform bear any responsibility, or does the buck stop entirely with the individual?
| Incident parameter | Logged / on-scene information |
|---|---|
| Date | 14 March 2025 |
| Time | 02:04:00 |
| Location | Holding room / processing area |
| Subject | Female in white tank top |
| Equipment | Intoxilyzer 8000 |
| Video source | AXON BODY 4 police bodycam |
| Reported context | "Heavily intoxicated" DoorDash driver |
Important note: The claim that the subject is a DoorDash driver is based on a text overlay added by the video's publisher and has not been independently verified.
Core questions still unanswered
- What was the result of the breath test, and was the driver charged?
- Was the driver actively on a delivery at the time of the incident?
- Which insurance policy will ultimately be responsible for any claims?
Learn more: Woman’s Hit-And-Run Panic Caught on Bodycam
🎥 Watch the video at the bottom of the page 👇
This story was edited from a publicly posted video; some details may not be independently verified.