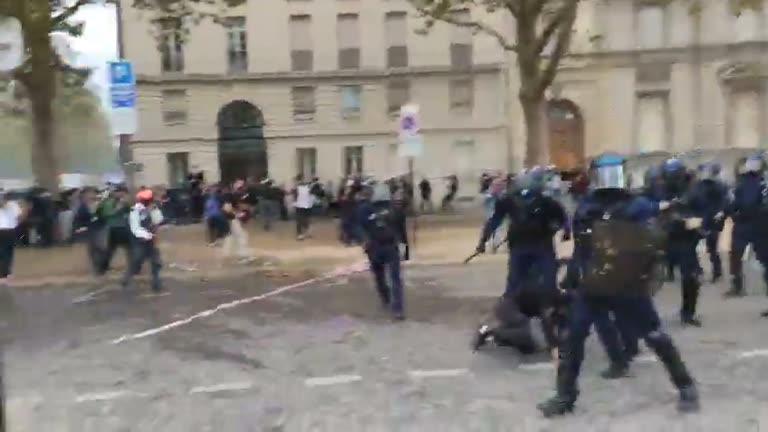
Dramatic footage captured on the streets of France shows the moment a police charge at Place Vauban descended into a chaotic scene, with an officer falling to the ground and a young protester being struck repeatedly while pinned down. The video, which has spread rapidly across social media, raises urgent questions about policing tactics, public liability, and who ultimately bears the financial cost when public order operations go wrong. As authorities face scrutiny over the events, the incident also shines a light on the complex insurance and compensation landscape that surrounds protests, injuries, and property damage in modern France.
Overview of the incident and the key facts
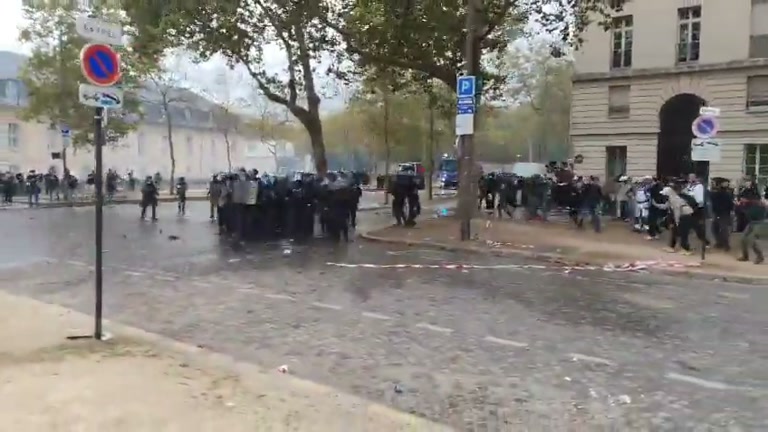
- The footage shows a police charge at Place Vauban in France, with officers in riot gear moving rapidly across a cobbled square.
- One police officer is seen falling to the ground during the charge, adding to the confusion and danger of the moment.
- A young protester is also brought to the ground and appears to receive several blows from officers without being formally arrested.
- The video has circulated widely online, prompting debate about proportional force and the treatment of people during demonstrations.
- The incident raises practical insurance questions for anyone injured, for property damaged, and for the authorities involved.
The charge and the fall on Place Vauban
The square at Place Vauban is not a grand boulevard or a landmark plaza that tourists flock to; it is an ordinary urban space, the kind of place where locals walk their dogs and students cut through on their way home. On this day, however, it became the stage for a confrontation that would be replayed thousands of times within hours. The footage opens with a line of officers in dark uniforms and helmets, their shields raised, moving forward in a coordinated surge across the wet cobblestones. There is little preamble; the charge is sudden, the kind of tactical manoeuvre that is designed to disperse a crowd quickly and decisively.
What follows is the detail that has made this clip travel so far: in the middle of that surge, one of the police officers loses his footing and crashes to the ground. It is a brief, almost ordinary moment of human clumsiness, but in the context of a charge, it is destabilising. Fellow officers nearby appear to adjust their movement; the rhythm of the advance falters for a beat. In the background, the blur of bodies and the grey light of an overcast afternoon give the scene an almost cinematic quality, as if the square itself is holding its breath. The viewer is left with the uncomfortable sense that even those trained and equipped for chaos are not immune to its randomness.
At the same time, the camera picks up a second figure: a young protester, dressed in dark clothing, who is brought down to the ground amid the surge. What follows is the most contentious part of the clip. The young man is on the ground, apparently not resisting, and yet several blows appear to be delivered by officers around him. Crucially, he is not arrested. He is not handcuffed, not led away, not processed. He is simply struck and left there as the charge continues. That single detail — force without arrest — is what has sparked the most heated debate online, because it cuts to the heart of what policing is supposed to achieve.
From an insurance perspective, this is not merely a question of ethics or optics. It is a question of liability. When a person is injured in a public order operation, the first question is who is legally responsible. In France, as in the UK and the US, that question is rarely straightforward. The state may enjoy certain immunities, but those immunities are not absolute. If a court finds that force was excessive or that an officer acted outside the scope of lawful duty, compensation can follow. But the road to that outcome is long, expensive, and littered with procedural hurdles that most injured people never manage to clear.
For the officer who fell, the situation is different but equally complicated. Police officers are typically covered by their employer's liability arrangements and by specific occupational injury schemes. In France, this may fall under the remit of the employer — the state — and the relevant social security framework. But the presence of an injury does not automatically mean a payout. The officer must demonstrate that the injury occurred in the course of duty, and the compensation will usually be calculated according to fixed schedules rather than the unpredictable logic of a civil lawsuit. It is a system designed for speed and predictability, not for the dramatic sums that occasionally make headlines in the US.
The blurred line between protest and liability
Protest is a protected activity in most democracies, but protection does not mean immunity from consequence. When demonstrations turn disruptive, the financial fallout spreads in multiple directions: injuries to protesters, injuries to officers, damage to public property, damage to private property, and the broader economic cost of disruption. The footage from Place Vauban sits precisely at the intersection of these concerns. It is not a riot in the classic sense — there are no burning cars or smashed shopfronts in the frames — but it is a confrontational public order operation, and that is enough to trigger a complex web of insurance considerations.
For the young man on the ground, the most immediate concern would be health. If he sustained injuries, the first port of call in France would be the national health insurance system, the Assurance Maladie. Unlike the US, where a hospital visit can generate bills running into tens of thousands of dollars, the French system is built on reimbursement and state funding. That does not mean it is free at the point of care, but it does mean that the financial shock is cushioned. However, state health cover does not compensate for pain, suffering, or lost earnings. For that, a separate claim would be needed, either through a civil action against the state or through a private insurance policy that includes legal protection.
This is where the UK and US systems diverge sharply, and it is worth pausing on the differences because they shape what happens next. In the UK, the police are covered by the Crown Proceedings Act, and claims against the police for assault or false imprisonment are usually brought in the civil courts. The time limits are strict — typically three years for personal injury — and the burden of proof rests on the claimant. In the US, by contrast, police officers often benefit from qualified immunity, a doctrine that makes it very difficult to sue unless a constitutional right has been clearly violated. The result is that many incidents that look shocking on video never result in compensation, not because the conduct was acceptable, but because the legal system is designed to make claims difficult.
Insurance policies themselves vary enormously. A standard home insurance policy in the UK will typically cover personal liability, but it will usually exclude liability arising from criminal acts or from participation in a riot. A travel insurance policy may cover medical expenses abroad, but it will rarely cover injuries sustained while taking part in a demonstration. A car insurance policy might cover damage to a vehicle if it is caught up in a protest, but only if the policyholder can show that they were not a participant. The common thread is that insurers are cautious about public order events, because they are unpredictable and because the legal responsibility is often contested.
For the police officer who fell, the pathway is more clearly defined. In France, police officers are covered by a specific scheme for occupational injuries, and they may also have access to additional cover through their union or professional association. In the UK, the Police Federation provides legal representation and support, and officers are covered by the employer's liability insurance. In the US, police officers typically have access to workers' compensation, which covers medical bills and a portion of lost wages, but which usually bars them from suing their employer. The key difference is that officers are almost always covered in some form, whereas protesters and bystanders often are not.
What the footage does and does not show
It is important to be precise about what the video actually captures, because the internet has a tendency to fill in gaps with speculation. The footage shows a charge, a fall, and a young man on the ground being struck. It does not show what happened before the charge, what was said, or what the crowd was doing. It does not show whether the young man was part of the protest or simply in the wrong place at the wrong time. It does not show whether he was injured, whether he sought medical attention, or whether he was later arrested or released. These are not minor details; they are the very facts that would determine any insurance claim or legal action.
The absence of that context is not a flaw in the video; it is the nature of viral footage. A clip is a window, not a panorama. But for anyone trying to understand the insurance and liability implications, the missing context is everything. Did the young man require hospital treatment? If so, was it paid for by the state or by private insurance? Did he lose income as a result of his injuries? If so, did he have income protection insurance? Did the officer who fell suffer a lasting injury? If so, will he be able to return to frontline duties, and what does that mean for his earnings? These are the questions that insurers and lawyers will ask, and they cannot be answered by watching a few seconds of footage.
There is also the question of property damage. The frames show a cobbled square, a few trees, and what appears to be a street sign. There is no obvious damage to buildings or vehicles. But protests often leave a trail of minor destruction — broken glass, graffiti, damaged street furniture — and those costs add up. In France, local authorities may be able to claim compensation from the state for damage caused during public order operations, but the process is bureaucratic and slow. In the UK, the Riot Compensation Act allows victims of riot damage to claim from the police authority, but the threshold for what counts as a riot is high. In the US, there is no equivalent federal scheme, and victims must rely on civil litigation or their own insurance.
For the average person watching this footage, the most practical takeaway is that insurance is not a magic wand. It is a contract with conditions, exclusions, and limits. A standard home insurance policy will not cover you if you are injured while participating in a demonstration. A health insurance policy will cover treatment but not compensation for pain and suffering. A legal expenses policy may help you pursue a claim, but it will not guarantee success. The gap between what people assume is covered and what is actually covered is where financial hardship lives.
The financial aftermath for those involved
If the young man on the ground decides to pursue compensation, the process would begin with a formal complaint, either to the police oversight body or through the courts. In France, the relevant body is the Inspection Générale de la Police Nationale, which investigates allegations of misconduct. If the complaint is upheld, the case may proceed to a civil claim. In the UK, the Independent Office for Police Conduct plays a similar role, and a successful claim could result in damages for assault, false imprisonment, or both. In the US, the process would typically begin with a civil rights lawsuit under Section 1983, which allows individuals to sue state officials for violations of constitutional rights.
But the reality is that most such claims fail, settle for modest amounts, or take years to resolve. The legal costs alone can be prohibitive, which is why legal expenses insurance is so valuable. A standalone legal expenses policy, often available as an add-on to home or motor insurance, can cover the cost of pursuing a claim, but it will usually only pay out if the claim has a reasonable chance of success. It will not fund a hopeless case, and it will not cover the other side's costs if the claim fails. This is the harsh arithmetic of civil justice, and it is why many people never pursue a claim at all.
For the officer who fell, the financial consequences are likely to be more contained. In France, the employer — the state — is responsible for covering medical costs and providing compensation for permanent injury. In the UK, the Police Federation offers support, and the employer's liability scheme provides cover. In the US, workers' compensation provides a no-fault system that pays medical bills and a portion of lost wages, regardless of who was at fault. The trade-off is that workers' compensation usually prevents the officer from suing anyone else, including the protester who may have caused the fall. It is a closed system, designed to provide certainty rather than maximum recovery.
There is also the question of reputational and financial risk for the authorities. A viral video of a chaotic charge can lead to political pressure, internal investigations, and — in some cases — financial settlements. The cost of those settlements is borne by the taxpayer, which means that the public ultimately pays twice: once for the policing operation, and again for the compensation. This is not a uniquely French phenomenon; it happens in the UK, the US, and across Europe. But it is a reminder that public order policing is not just a matter of tactics and equipment; it is a matter of money, and the money always comes from somewhere.
For the insurance industry, incidents like this are a reminder of why certain risks are excluded from standard policies. Public order events are unpredictable, politically charged, and often involve multiple parties with competing claims. Insurers prefer risks that can be quantified and priced. A protest, by contrast, is a black box. That is why many policies exclude riot, civil commotion, and participation in demonstrations. It is not a moral judgement; it is an actuarial one. The result is that the people most likely to be injured in these events are often the least likely to be compensated.
Insurance and who pays
If you are injured in a public order event in France, the first layer of financial protection is the state health insurance system, which reimburses a significant portion of medical costs. But reimbursement is not the same as compensation. To recover lost earnings, pain and suffering, or future care costs, you would need to pursue a civil claim, and that requires legal representation. Legal expenses insurance, often sold as an add-on to home or motor policies, can fund that representation, but it will only do so if the claim has a reasonable prospect of success. It is not a guarantee, and it does not remove the risk of losing.
In the UK, the picture is similar but with different institutions. The NHS provides free-at-the-point-of-use healthcare, but again, it does not compensate for lost income or pain. A personal injury claim against the police would be brought under tort law, and the time limit is three years. Legal expenses insurance is widely available, and many home insurance policies include it as standard. However, as in France, the policy will usually exclude claims arising from criminal acts or from participation in a riot. If you were simply a bystander, you may have a stronger position, but you would still need to prove that the police owed you a duty of care and that they breached it.
In the US, the system is more fragmented. Health insurance is often tied to employment, and a serious injury can lead to medical bills that run into hundreds of thousands of dollars. Legal expenses insurance is less common, and civil rights claims are complex and expensive. Qualified immunity means that many claims are dismissed before they reach a jury. For the officer who fell, workers' compensation is the primary route, and it covers medical costs and a portion of lost wages. For the protester, the route is far less certain, and the financial risk is far higher.
The excess, or deductible, is another factor that is often overlooked. Even if a claim is successful, the policyholder may have to pay the first portion of any loss out of their own pocket. In the UK, a typical home insurance excess is around £100 to £250, while a motor excess can be £250 to £500. In the US, deductibles are often higher, sometimes $500 to $1,000 for home insurance and more for health insurance. These amounts are not trivial, and they can be the difference between making a claim and absorbing the loss. For someone who is already dealing with injury or disruption, that calculation can be brutal.
The steps for making a claim are broadly similar across all three countries. First, report the incident to the relevant authority — the police, the insurer, or both. Second, gather evidence: photographs, witness statements, medical records, and any correspondence. Third, notify your insurer as soon as possible, because late notification can invalidate a claim. Fourth, cooperate with the investigation and provide any documentation requested. Fifth, if the claim is disputed, consider whether legal action is worth the cost and risk. It is a process that rewards patience and penalises haste, and it rarely produces a quick or clean outcome.
For the people at the centre of this footage, the financial consequences may take months or years to unfold. The video will continue to circulate, the debate will continue, and the insurance claims — if there are any — will proceed quietly in the background. That is the nature of these events: the drama is public, but the money is private.
What do you think should happen when force is used without an arrest — and who should ultimately foot the bill when public order operations go wrong?
| Incident parameter | Logged / on-scene information |
|---|---|
| Location | Place Vauban, France |
| Event type | Police charge during public order operation |
| Officer down | One police officer fell during the charge |
| Protester on ground | A young man was struck without being arrested |
| Video source | Publicly posted social media clip |
| Official conclusion | None confirmed |
| Insurance relevance | Injury, liability, legal expenses |
Important note: Some details, including the identities of those involved and any official investigation, remain unverified.
Core questions still unanswered
- Was the young man injured, and did he file a complaint?
- Did the officer who fell suffer a lasting injury?
- Has any official investigation been opened into the conduct shown?
Learn more: Drunk Driving Suspect Claims Setup in Viral Bodycam Footage
🎥 Watch the video at the bottom of the page 👇
This story was edited from a publicly posted video; some details may not be independently verified.