A late-night gathering at a petrol station forecourt became the backdrop for a tense confrontation that has since drawn attention online. What began as a noisy meet-up in the artificial glare of the canopy lights shifted into a confrontation that left bystanders watching and, later, commenters arguing over who bore responsibility. The footage captures the uneasy moment a group closed in — and the split-second reactions that followed.
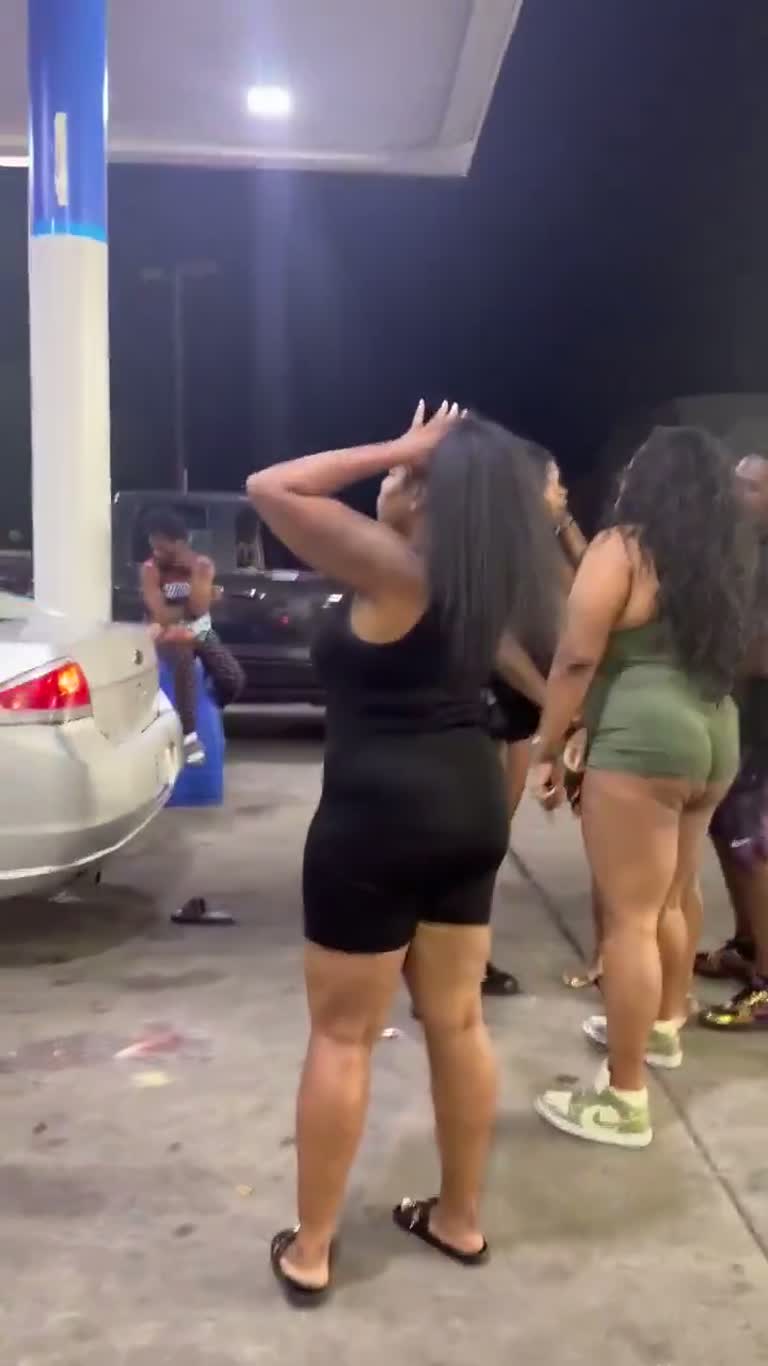
Watch Full Video
Overview of the incident and the key facts
- The incident unfolds at night on a concrete petrol station forecourt under bright canopy lighting.
- A group of people is captured on camera as a confrontation develops around one woman.
- A man is seen seated on the back of a white car, watching the scene unfold.
- The exchange sharpens when the woman raises her hands to her head in a gesture of frustration.
- Passers-by and onlookers remain in the frame as the group's movements shift across the forecourt.
The footage opens on a petrol station forecourt at night, the concrete reflecting the hard white glare of overhead canopy lights, with a white saloon car parked to the left of frame and a dark vehicle sitting further back.
A group of people, predominantly women, is standing in a loose cluster; a man in a basketball-style vest and patterned trousers walks past the camera, while another man sits on the edge of a blue bollard or barrier.
The central figure is a woman in a black top and black shorts who raises both hands to her head in a gesture of evident frustration or disbelief.
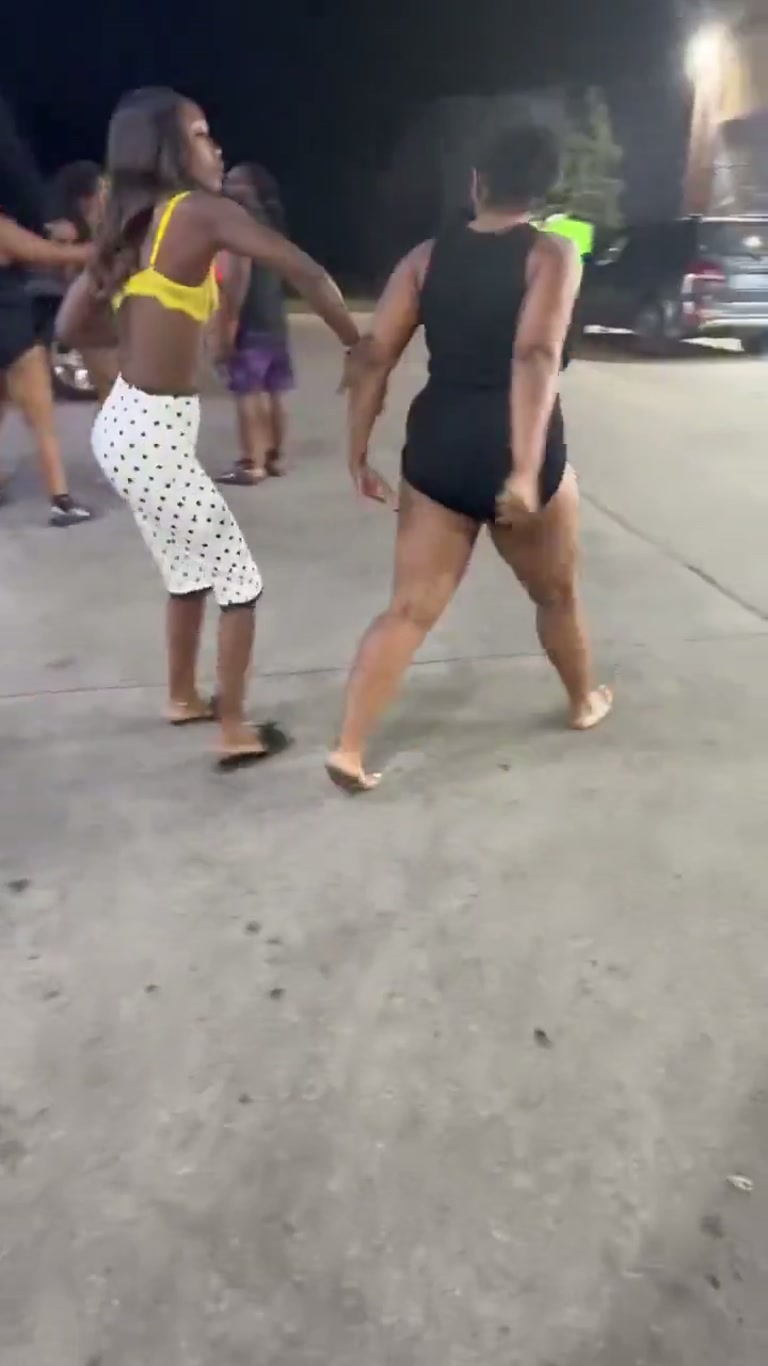
A second woman in a green two-piece stands nearby, and others in the group shift and turn as the situation develops; the woman in the yellow top and polka-dot trousers becomes a focus of the movement.
The audio captures only a fragment — "Real cold, get together" — so the full dialogue is not available, and no official account of what preceded or followed the clip has been released.
A forecourt at night, and a group that would not disperse
The first thing that strikes you about the clip is the ordinariness of the setting. A petrol station forecourt after dark is one of the most mundane places imaginable — a place of quick stops, coffee runs and windscreen squeegees. But in the harsh floodlights, the concrete takes on a strange, stage-like quality, and the people standing in the middle of it suddenly look less like customers and more like a scene unfolding in front of an audience. The white car to the left sits with its lights still glowing, a silent witness to whatever is happening.
What the footage shows is a gathering that seems to have taken on a life of its own. There is no indication that anyone in the group is there to buy fuel. Instead, they are clustered, talking, turning, watching one another. The man sitting on the barrier adds to the sense of a pause — someone choosing to observe rather than intervene. And then there is the woman in black, both hands going to her head, a gesture that every viewer recognises instantly: something has gone wrong, and she is trying to process it.
The energy shifts again as the woman in the yellow top and polka-dot trousers moves across the frame. The camera stays on her, and the group's attention follows. There is no pushing, no shouting that the audio captures, but the body language is unmistakably tense. When a group surrounds an individual, even without physical contact, the dynamics of power and pressure change. The person at the centre can feel outnumbered, and onlookers can feel unsure whether to step in or step back.
It is that ambiguity — the gap between what we can see and what we cannot know — that has made the clip travel. Nobody in the frame is identified. No police report has been confirmed. The audio gives us one fragment and nothing more. What we are left with is a snapshot of human behaviour under pressure: the way people close ranks, the way one person's frustration becomes a group's problem, and the way an ordinary forecourt becomes a stage.
The bystander question: when to watch and when to step in
Every public confrontation raises the same uncomfortable question. If you are standing nearby, do you intervene? Do you film? Do you leave? The forecourt in this clip is not empty. There are vehicles, there is open space, and there are people who appear to be watching rather than participating. That is not a criticism — it is a reality of modern public life. Most of us are not trained for conflict, and most of us hesitate.
But the presence of onlookers matters, both socially and legally. In the UK, there is no general legal duty to rescue a stranger in distress, but there are specific duties in certain relationships and roles. In the US, the picture varies state by state, with some states imposing a duty to report certain crimes and others adhering more strictly to the no-duty-to-rescue principle. What is common to both is that once a person does choose to act, their conduct is judged against a reasonableness standard — and that is where liability can begin.
The clip also raises the question of what the people involved understood about their own risk. A petrol station is not a private living room. It is a commercial premises with its own rules, its own insurance, and its own exposure to liability. If a confrontation on the forecourt escalates into injury or property damage, the consequences do not stay contained to the people in the frame. They ripple outward to the business, to insurers, and sometimes to the courts.
That is why clips like this are not just entertainment. They are windows into how quickly an ordinary night can become a legal and financial event. The woman with her hands to her head, the group around her, the man on the barrier, the cars waiting in the background — all of them are part of a chain of decisions that could, in the wrong circumstances, end in a claim rather than a comment thread. The footage does not tell us whether that happened here, and no official conclusion has been released. But it is a reminder that public spaces carry hidden costs.
The insurance angle: what a forecourt incident can trigger
If a confrontation on a petrol station forecourt leads to injury or damage, several types of insurance can come into play, and the average viewer rarely thinks about them until they need them. The first is motor insurance. If a vehicle is damaged during a scuffle — a door kicked, a mirror broken, a panel dented — the owner would typically look to their comprehensive policy, if they hold one. In the UK, comprehensive cover is the most common form, and it can respond to damage caused by a third party, but the insurer will usually expect the policyholder to provide details of the incident and may pursue recovery from the responsible party. In the US, cover varies by state and by whether the policy is liability-only or full coverage.
The second is public liability insurance, which is often held by the business operating the petrol station. If a customer or bystander is injured on the premises because of the way the site is managed — poor lighting, obstructed exits, failure to intervene in a known risk — the business's public liability policy may respond. This is not the same as saying the business is at fault. It means that, where negligence can be established, the policy is designed to meet the cost of defending and settling claims. Petrol stations typically carry this cover because they are open to the public and because incidents involving vehicles, fuel and crowds are foreseeable risks.
The third is personal accident or health insurance, depending on the jurisdiction. In the UK, the NHS means that emergency treatment is free at the point of use, but ongoing care, lost earnings and rehabilitation are not automatically covered. In the US, health insurance is central to how medical costs are handled, and a dispute over who pays can follow an incident for months. If the injury is serious, the difference between a policy that covers it and one that does not can be life-changing.
Then there is the question of liability itself. In both the UK and the US, a claim generally requires proof that someone owed a duty of care, that the duty was breached, and that the breach caused the loss. A video clip can be powerful evidence, but it rarely tells the whole story. It may not show who threw the first punch, who was provoked, or what was said. That is why insurers and lawyers are cautious about drawing conclusions from short clips — and why the public should be too. No official conclusion has been released about this incident, and no compensation has been confirmed.
Excess, exclusions and the steps that follow
For anyone who has ever made a claim, the word "excess" is familiar. In the UK, the excess — or deductible in US terms — is the amount the policyholder pays before the insurer covers the rest. On a motor policy, it might be £250 or £500 for accidental damage, and often more for younger drivers. On a home or contents policy, it might be £100 or £250. On a commercial public liability policy, the excess can run into thousands, because the insurer expects the business to absorb smaller incidents itself. That figure matters enormously in practice, because it determines whether a claim is worth making at all.
Exclusions matter just as much. A standard motor policy may exclude damage arising from a deliberate act, from racing, or from use of the vehicle outside the terms of the policy. A public liability policy may exclude claims arising from criminal acts or from events the business could not reasonably have foreseen. A health policy may exclude injuries sustained during the commission of a crime. These exclusions are not fine print for the sake of it; they are the boundaries of the risk the insurer agreed to carry, and they are tested hardest in exactly the kind of chaotic, ambiguous situation captured in this clip.
If a claim is made, the usual steps are consistent on both sides of the Atlantic. Report the incident promptly, both to the police where appropriate and to the insurer. Gather evidence — photographs, CCTV, witness details, registration numbers. Keep receipts for any emergency repairs or medical costs. Do not admit liability, and do not negotiate directly with the other party's insurer without advice. Cooperate with the insurer's investigation, and be honest about what you saw and did, because misrepresentation can void a policy entirely. These steps sound bureaucratic, but they are the difference between a claim that is paid and one that is refused.
Finally, there is the question of consumer protection. In the UK, the Financial Conduct Authority regulates insurers and requires fair treatment of customers, and the Financial Ombudsman Service can review disputes. In the US, state insurance departments regulate policies and handle complaints. These protections exist because the power imbalance between an individual and an insurer is real. But they only work if the individual knows they exist and uses them. For anyone caught up in a public incident like this one, that knowledge is not a luxury — it is a form of self-defence.
Insurance and who pays
The insurance dimension of an incident like this is rarely straightforward, and it is worth walking through it carefully, because the average reader's instinct — "surely someone's insurance covers it" — is often wrong. The first question is whose policy responds. If a vehicle is damaged, the owner's motor insurer is usually the first port of call, but the insurer will want to know whether the damage was accidental, deliberate, or the result of a criminal act. Deliberate damage is often covered under comprehensive policies, but the insurer will then seek to recover the cost from the person responsible, which means the claim may end up in court. If the responsible party cannot be identified or has no assets, the policyholder may still face their excess and a loss of no-claims discount.
If a person is injured, the route depends on where they are and what cover they hold. In the UK, the NHS handles emergency care, but a personal injury claim would generally be pursued against the party alleged to be at fault, with their public liability or motor insurer potentially meeting the cost. In the US, health insurance is the first payer for treatment, and the injured party may later pursue a liability claim to recover costs, lost wages and pain and suffering. The two systems produce very different outcomes for the same event, which is why cross-border comparisons can be misleading.
The business operating the petrol station has its own exposure. Public liability insurance is standard for premises open to the public, but it responds to the business's legal liability, not to every incident that happens on site. If the business took reasonable steps — lighting the forecourt, training staff, calling the police when needed — it may have no liability at all. If it ignored a known risk, the picture changes. Insurers will investigate, and the outcome will depend on evidence that a short clip rarely provides. Nothing in the footage establishes fault on anyone's part.
The practical lesson for the public is simple. Keep records. Report incidents. Understand your excess. Read the exclusions before you need them. And remember that a viral clip is not a court judgment. It is a starting point for questions, not an answer. The people in this footage may never make a claim, and the business may never face one. But if they do, the difference between being covered and being exposed will come down to documents, deadlines and details — not to who was loudest on the night.
| Incident parameter | Logged / on-scene information |
|---|---|
| Location | Petrol station forecourt, town unconfirmed |
| Time of day | Night, under canopy lighting |
| People visible | A group including a woman in black and a woman in green |
| Vehicles | White saloon car, dark vehicle in background |
| Audio | "Real cold, get together" |
| Outcome | No confirmed injury or official report |
| Source status | Publicly posted clip, unverified |
Important note: Some details in this account remain unverified because no official report or named source has confirmed the full sequence of events.
Core questions still unanswered
- What do you think actually triggered the confrontation on the forecourt?
- Should bystanders be expected to intervene in situations like this, or is filming the safer choice?
- If damage or injury had occurred, whose insurance do you think should pay?
Learn more: Night-time Van Incident Sparks Viral Conscription Debate
🎥 Watch the video at the bottom of the page 👇
This story was edited from a publicly posted video; some details may not be independently verified.